A unanimous hike, with inflation still elevated
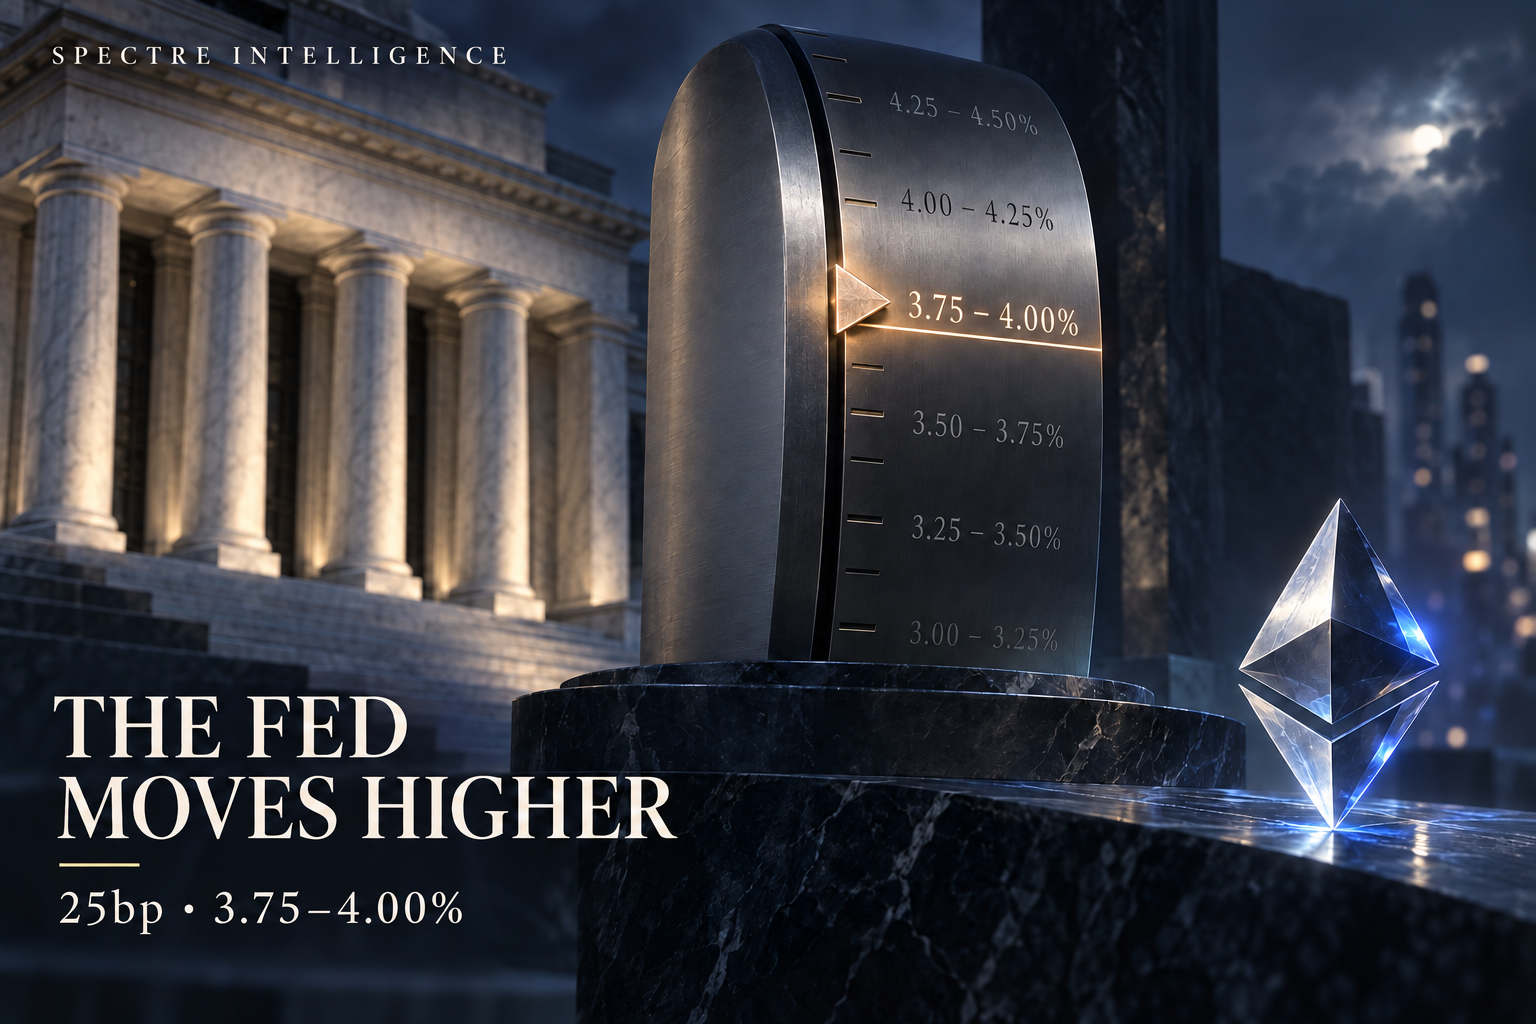
The Federal Reserve raised its target range by a quarter percentage point to 3.75–4.00% on September 16. The decision was unanimous, 12–0, in the statement released at 2:00 p.m. Eastern, or 18:00 UTC. The Committee described economic activity as expanding at a solid pace and said the increase would help inflation return to its 2% goal sooner. 1
That is a hawkish policy action: borrowing costs are moving higher to restrain inflation. Whether the announcement is a hawkish surprise requires a comparison with expectations immediately before release. An increase that investors anticipated can be followed by a rally; the price response alone cannot establish how much tightening was already reflected in markets.
The projected rate path moves higher
The September projections put the median end-2026 federal funds rate at 4.1%, compared with 3.8% in June. For end-2027, the median rises to 4.1% from 3.6%. These figures describe projected target midpoints or target levels, rounded to one decimal place. They are different from the upper bound of the newly announced 3.75–4.00% range. 2
The 2026 distribution contains 12 participants at a 4.125% midpoint, four at 4.375%, and two at 3.875%. Sixteen of the 18 participants therefore project a year-end midpoint above the new range’s 3.875% midpoint. The projections express individual judgments about appropriate policy; they do not bind the Committee to another increase. 2
The median 2026 PCE inflation projection rises to 3.7% from 3.6% in June, while unemployment falls to 4.1% from 4.3%. Taken together with the higher rate path, those revisions suggest policymakers see room to keep pressure on inflation while employment holds up. That interpretation concerns the published forecasts, not a verified reading of Kevin Warsh’s spoken remarks. 2
ETH recovers the first drop, then pulls back
On Coinbase Exchange, ETH-USD closed the 17:59 UTC minute at $2,387.34. The 18:00 release-minute candle reached a low of $2,366.69. A subsequent trade at 18:07:41 UTC was $2,416.34: about 1.21% above the pre-release minute close and 2.10% above that release-minute low. Those are two different comparisons, and both matter when describing a rebound. 3
By the next saved ticker observation, at 18:16:02 UTC, ETH was $2,401.24. It had surrendered about 0.62% from the earlier $2,416.34 observation but remained roughly 0.58% above the pre-release close. The initial recovery was real in this sample; its follow-through was already uneven. 3
These observations cover one exchange and a short event window. They do not establish why traders bought, prove a short squeeze, or measure the whole day’s move. A lasting recovery would require evidence beyond the first few minutes. Price strength also cannot substitute for reading the Fed’s statement and the chair’s answers.
What Warsh’s guidance needs to clarify
The distinction to watch is whether Warsh presents the increase as sufficient for now or leaves a clear case for further tightening. His assessment of persistent inflation, and the conditions that would change that assessment, would help explain the rate projections. A softer or firmer message should be judged against the published decision and the expectations entering the meeting.
This initial edition analyses the statement and projections. It does not assign a dovish or hawkish label to an unverified press-conference passage. Any assessment of the spoken guidance needs attributable remarks, their time, and enough surrounding context to avoid turning a conditional answer into a policy promise. The Fed’s meeting page is the primary reference for its conference materials. 4
CLARITY remains part of the background
The Fed decision follows the September 15 CLARITY setback. Spectre’s report, based on the Senate Daily Press’s completed result, recorded a 49–50 failure of cloture on the motion to proceed to H.R.3633. That was a failed attempt to advance consideration, not a final vote rejecting the legislation. The report also recorded a possible route to reconsideration. 5, 6
That legislative uncertainty belongs alongside the monetary-policy analysis. A potential return to the Senate floor is not enacted regulatory clarity, and a rising ETH price does not resolve either question. This edition makes no claim that a subsequent reconsideration has been scheduled or succeeded. 5
Sources
- Federal Reserve: September 16, 2026 FOMC statement, released 14:00 EDT
- Federal Reserve: September 2026 economic projections, Table 1 and Figure 2
- Preserved Coinbase ETH-USD trades, minute candles and percentage calculations
- Federal Reserve: September 16 press-conference materials
- Spectre’s September 15 sourced CLARITY result and procedural analysis
- U.S. Senate: filibusters and cloture
See a discrepancy? Send the article URL and supporting evidence to spectre@spectreai.io.
Explore Spectre